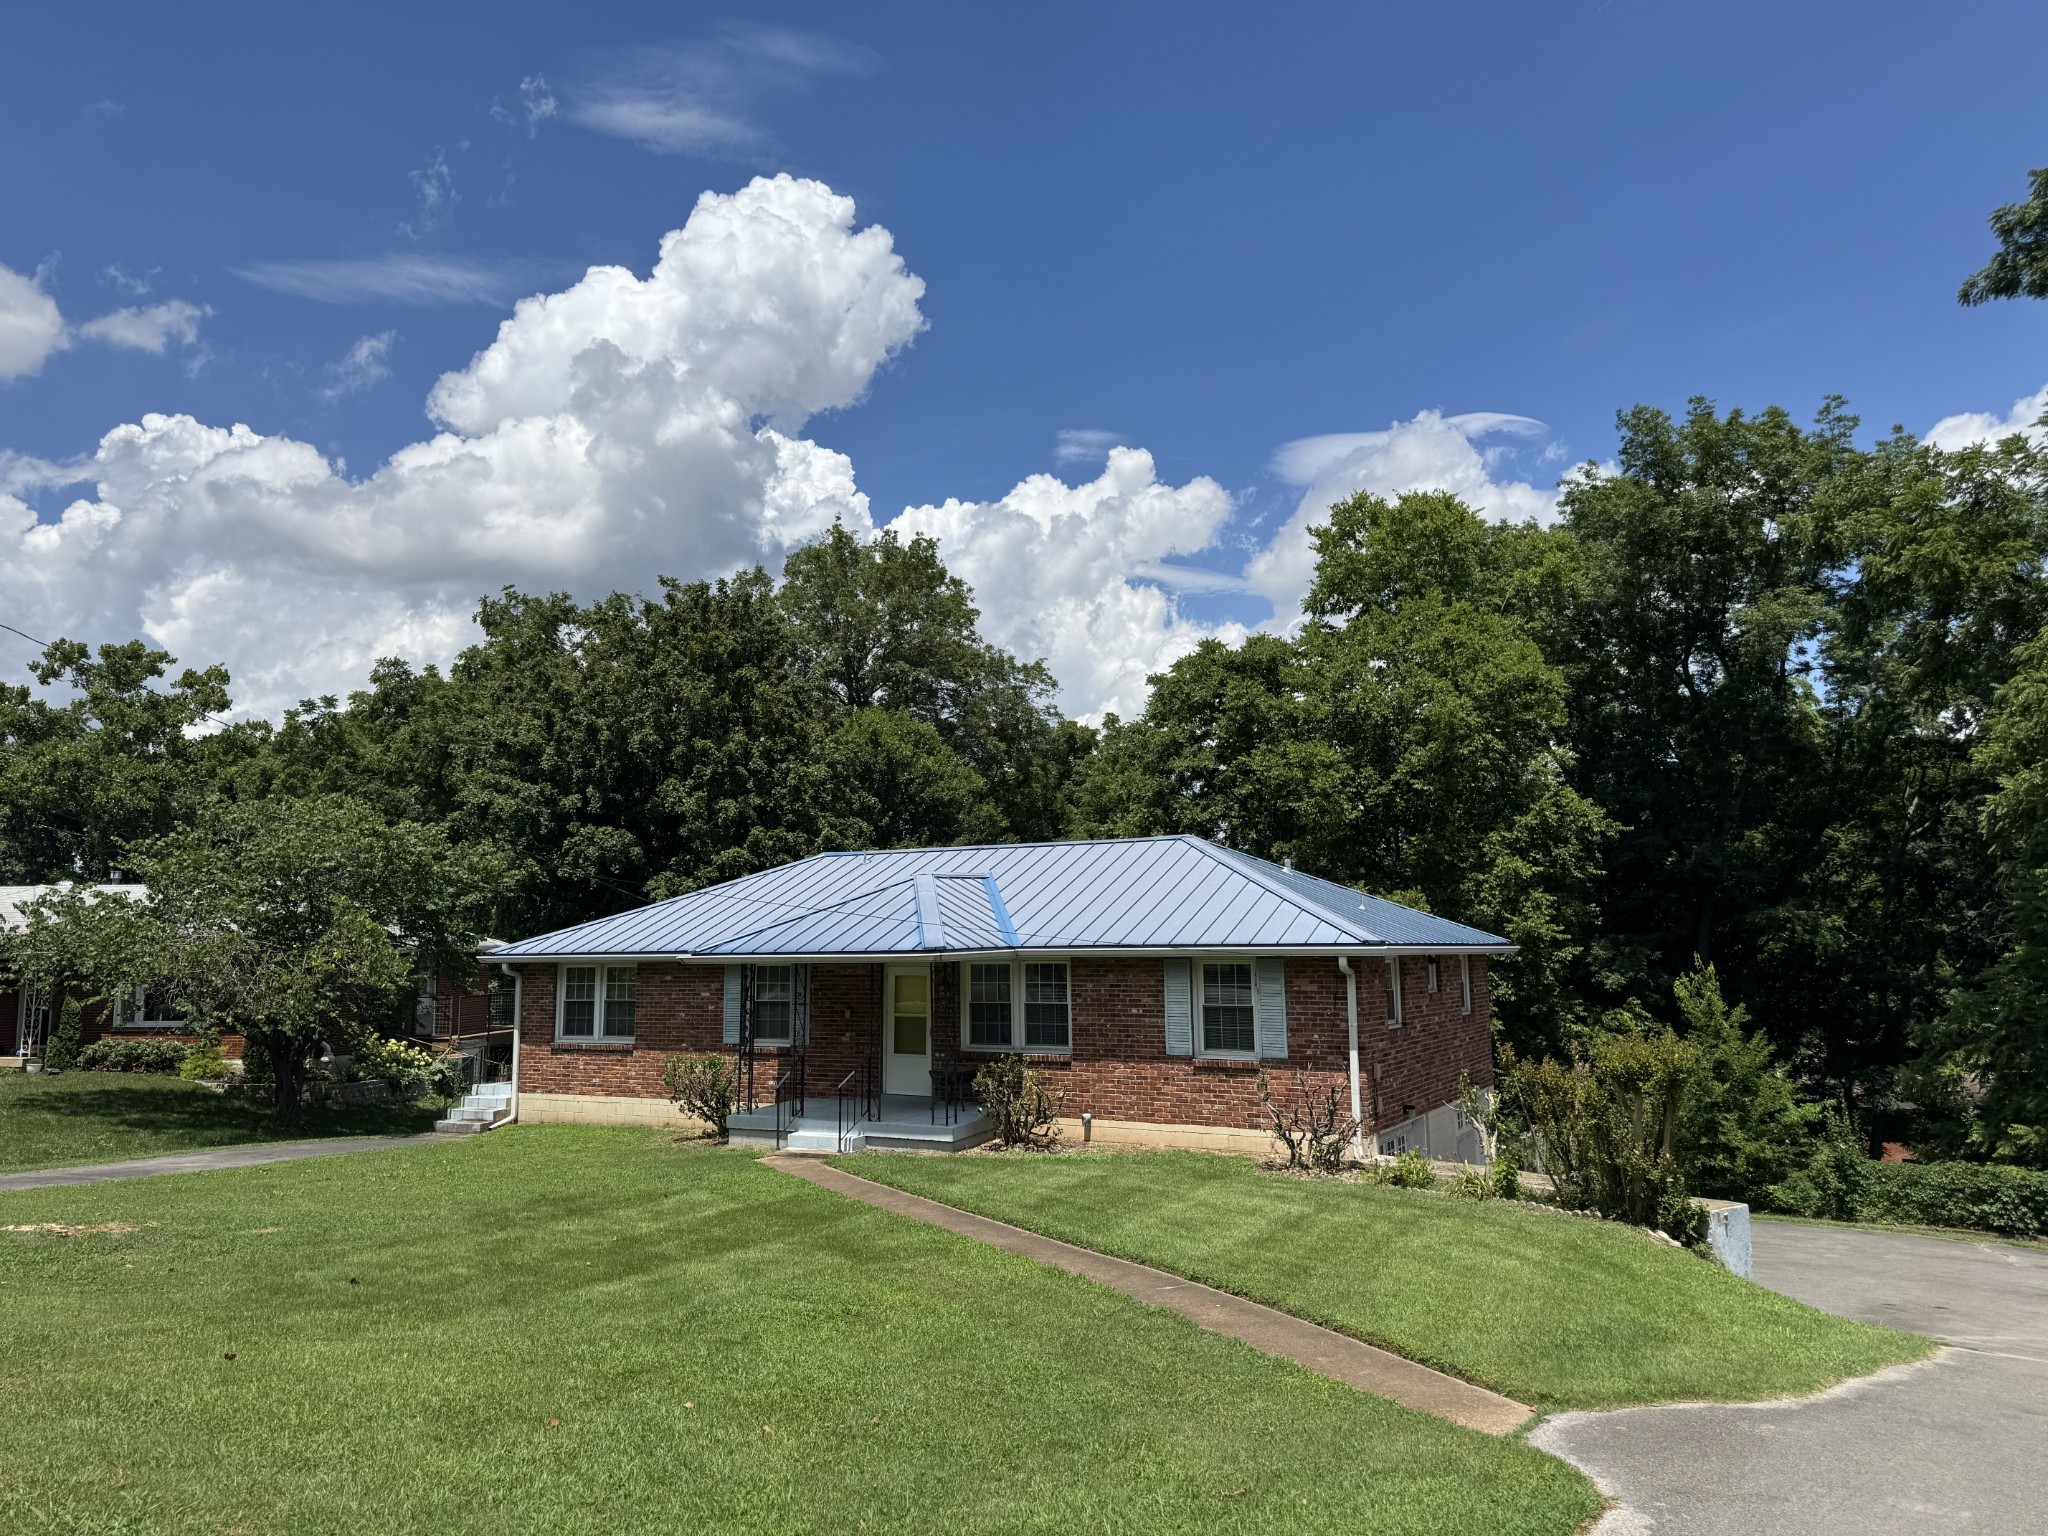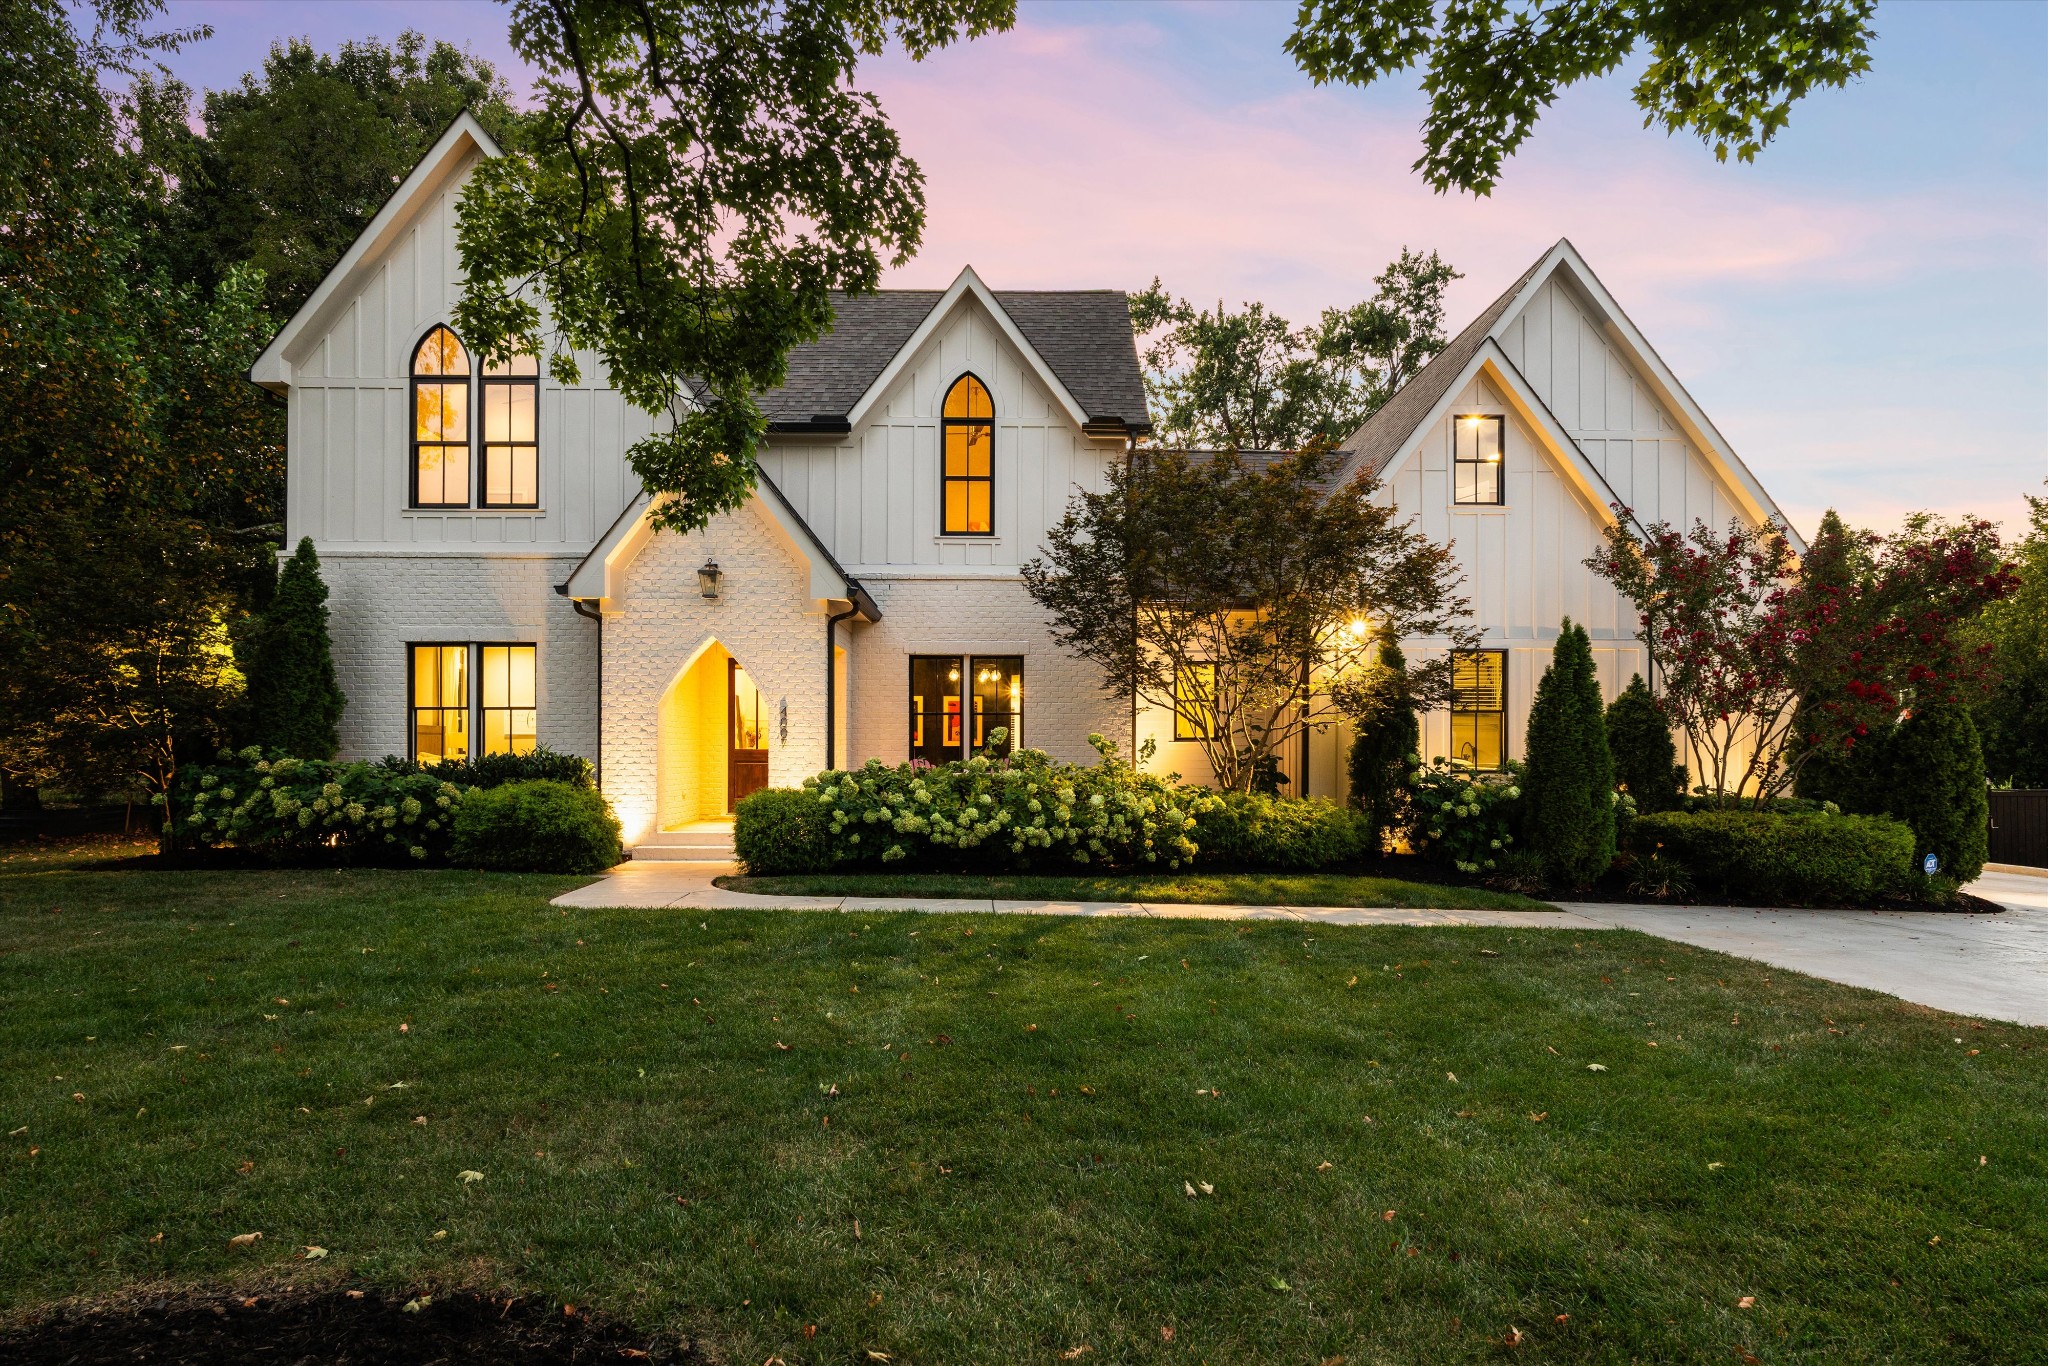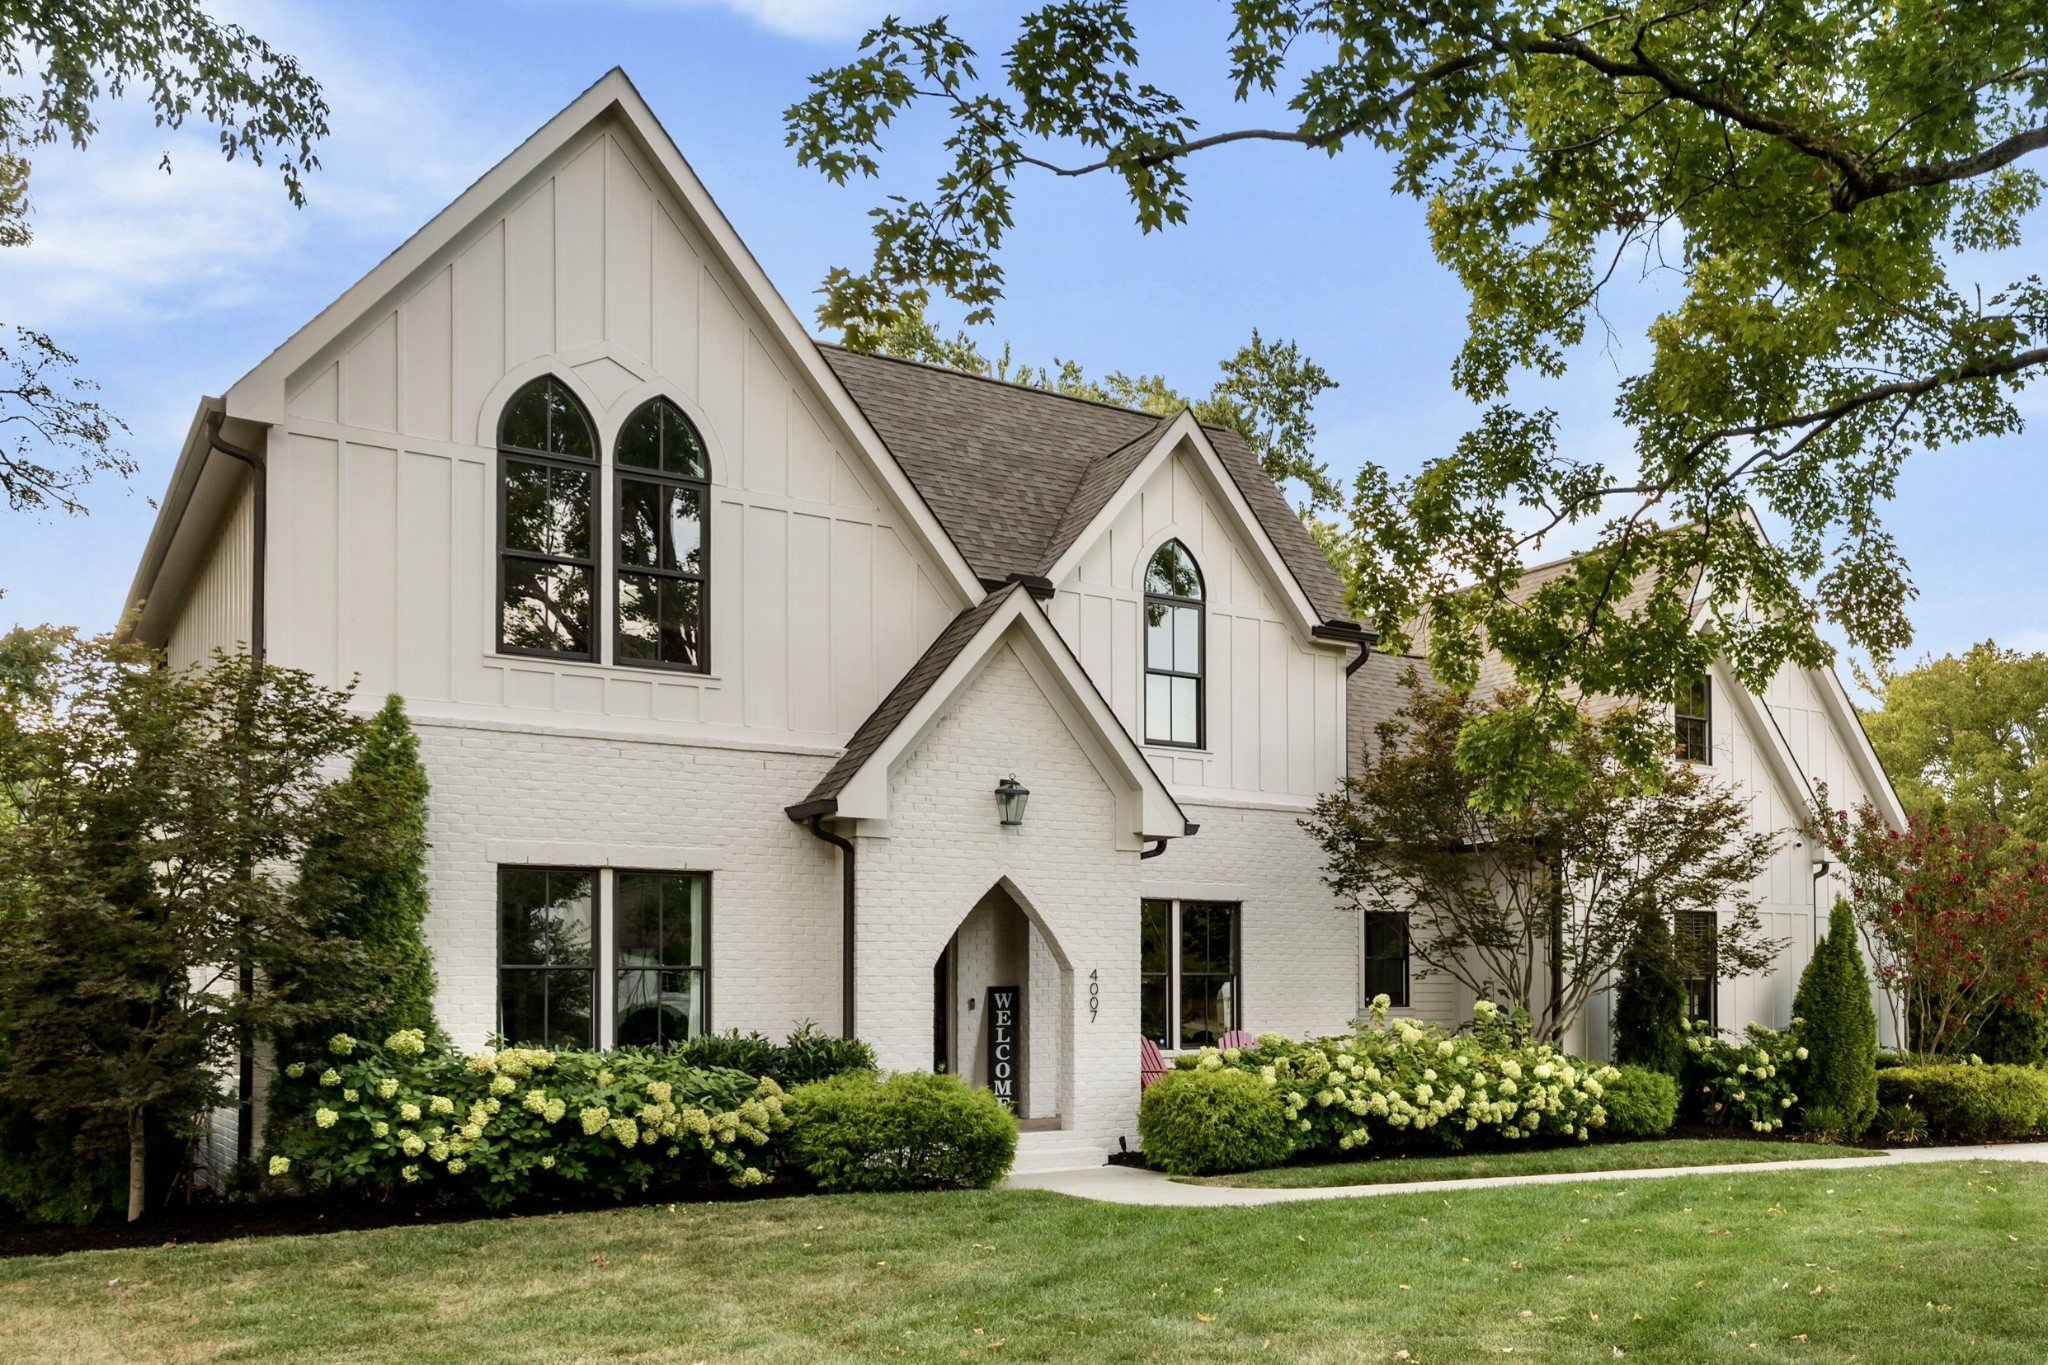


New - 3 Hours Ago
$359,900
Active
2
Beds
1
Baths
992
Sqft
--
Acres
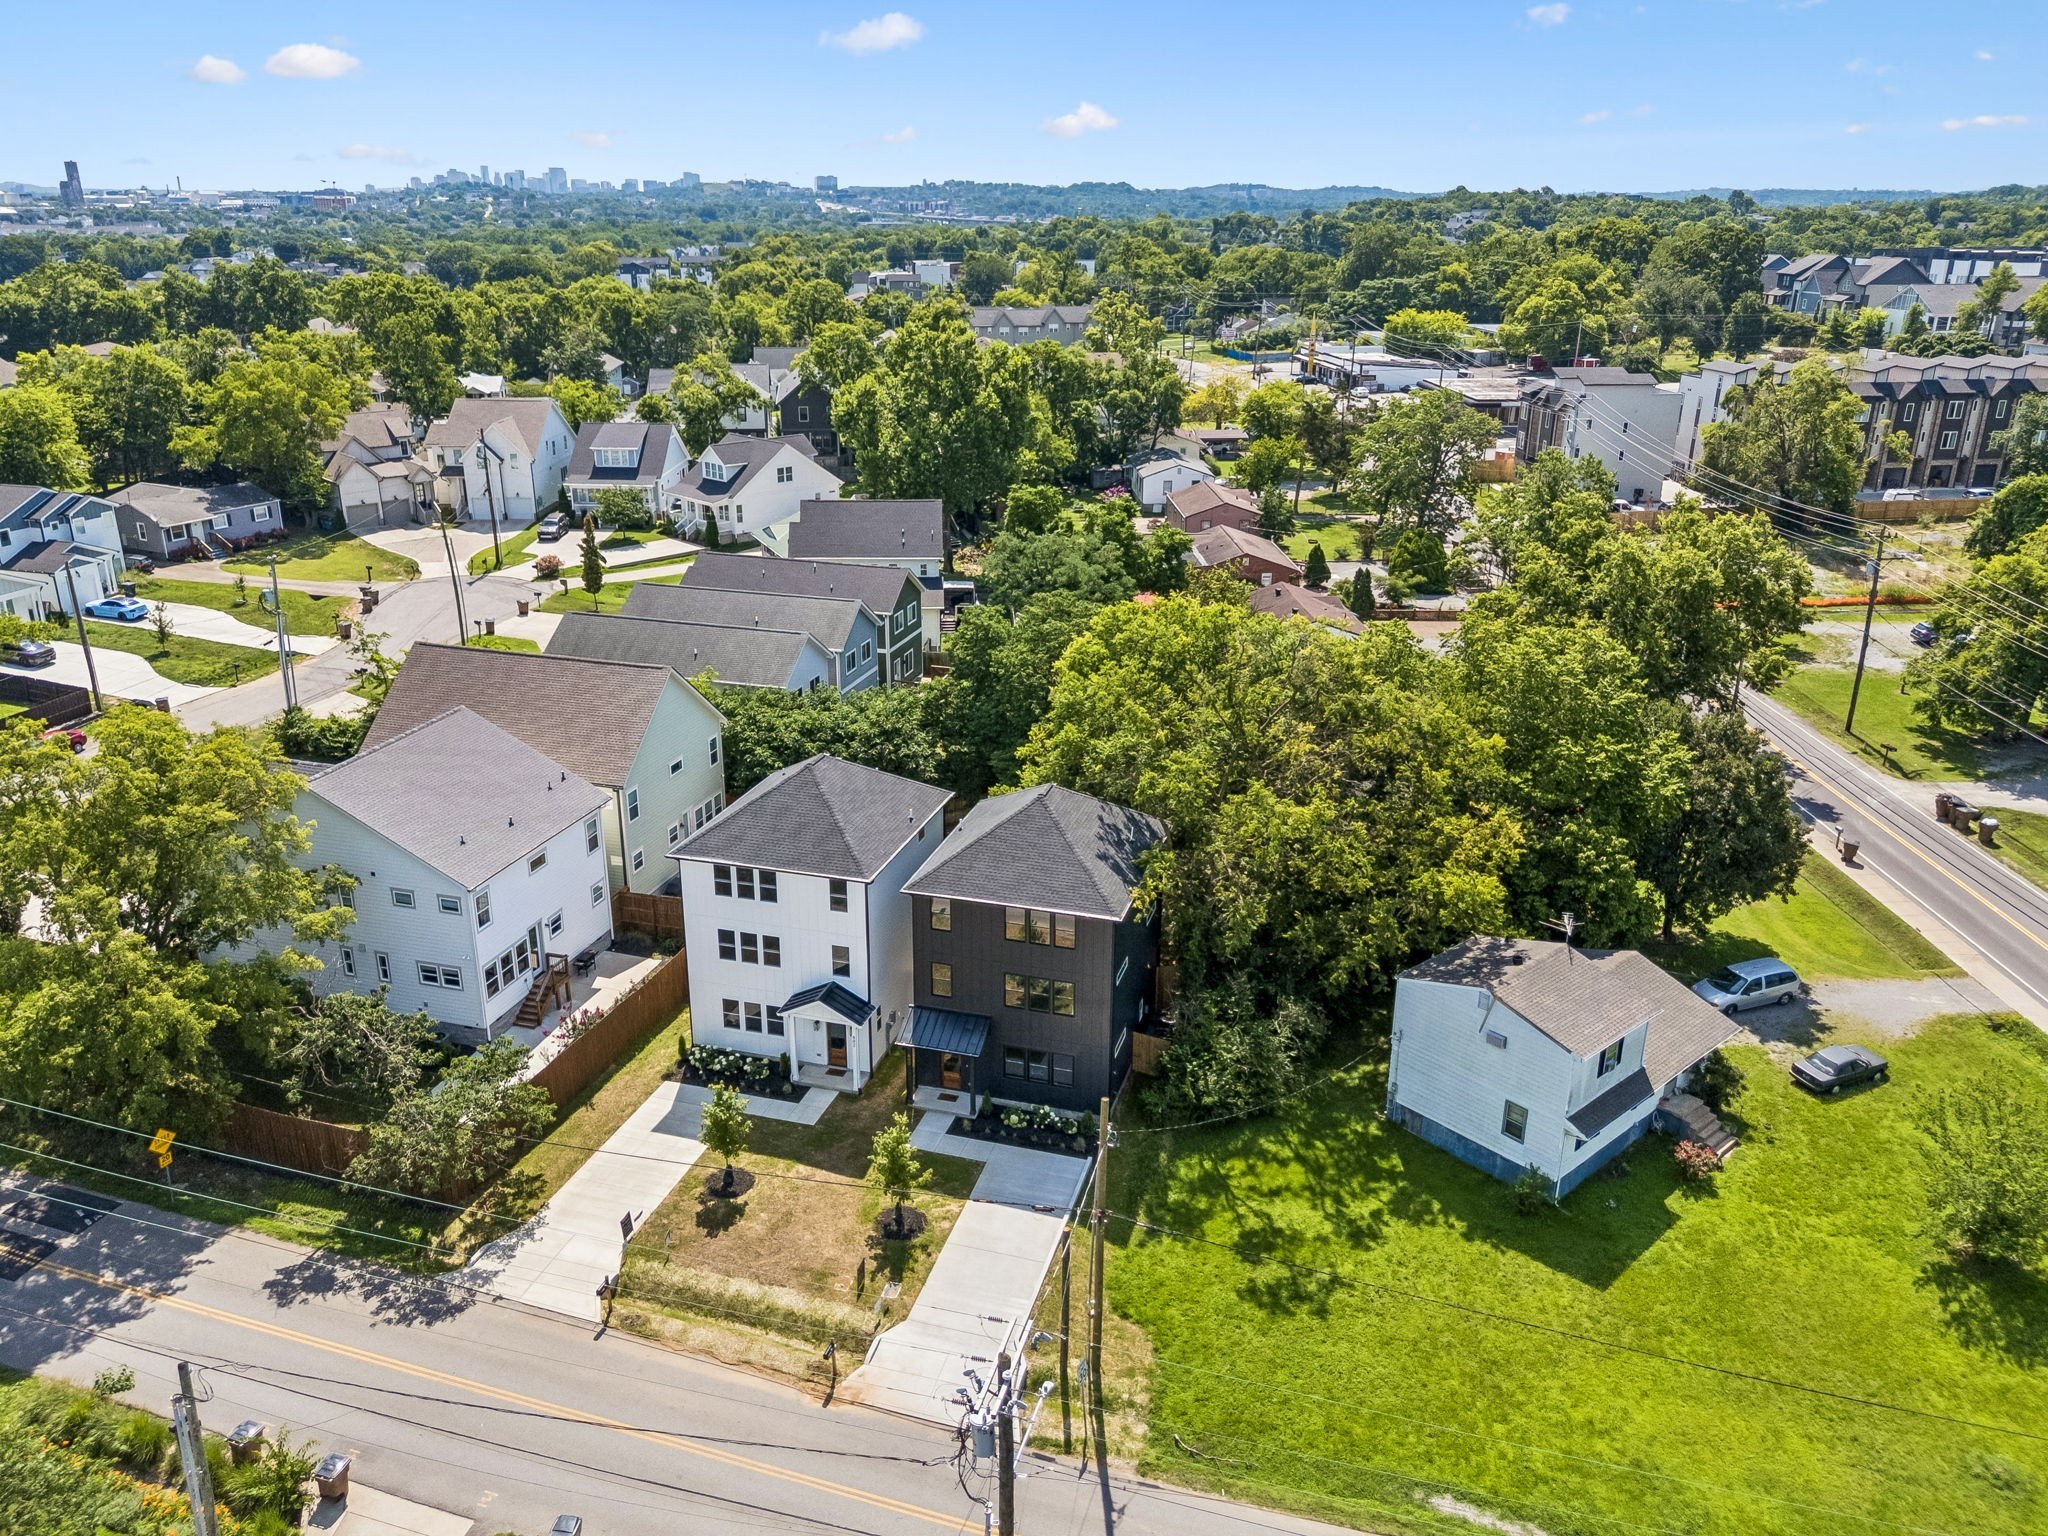
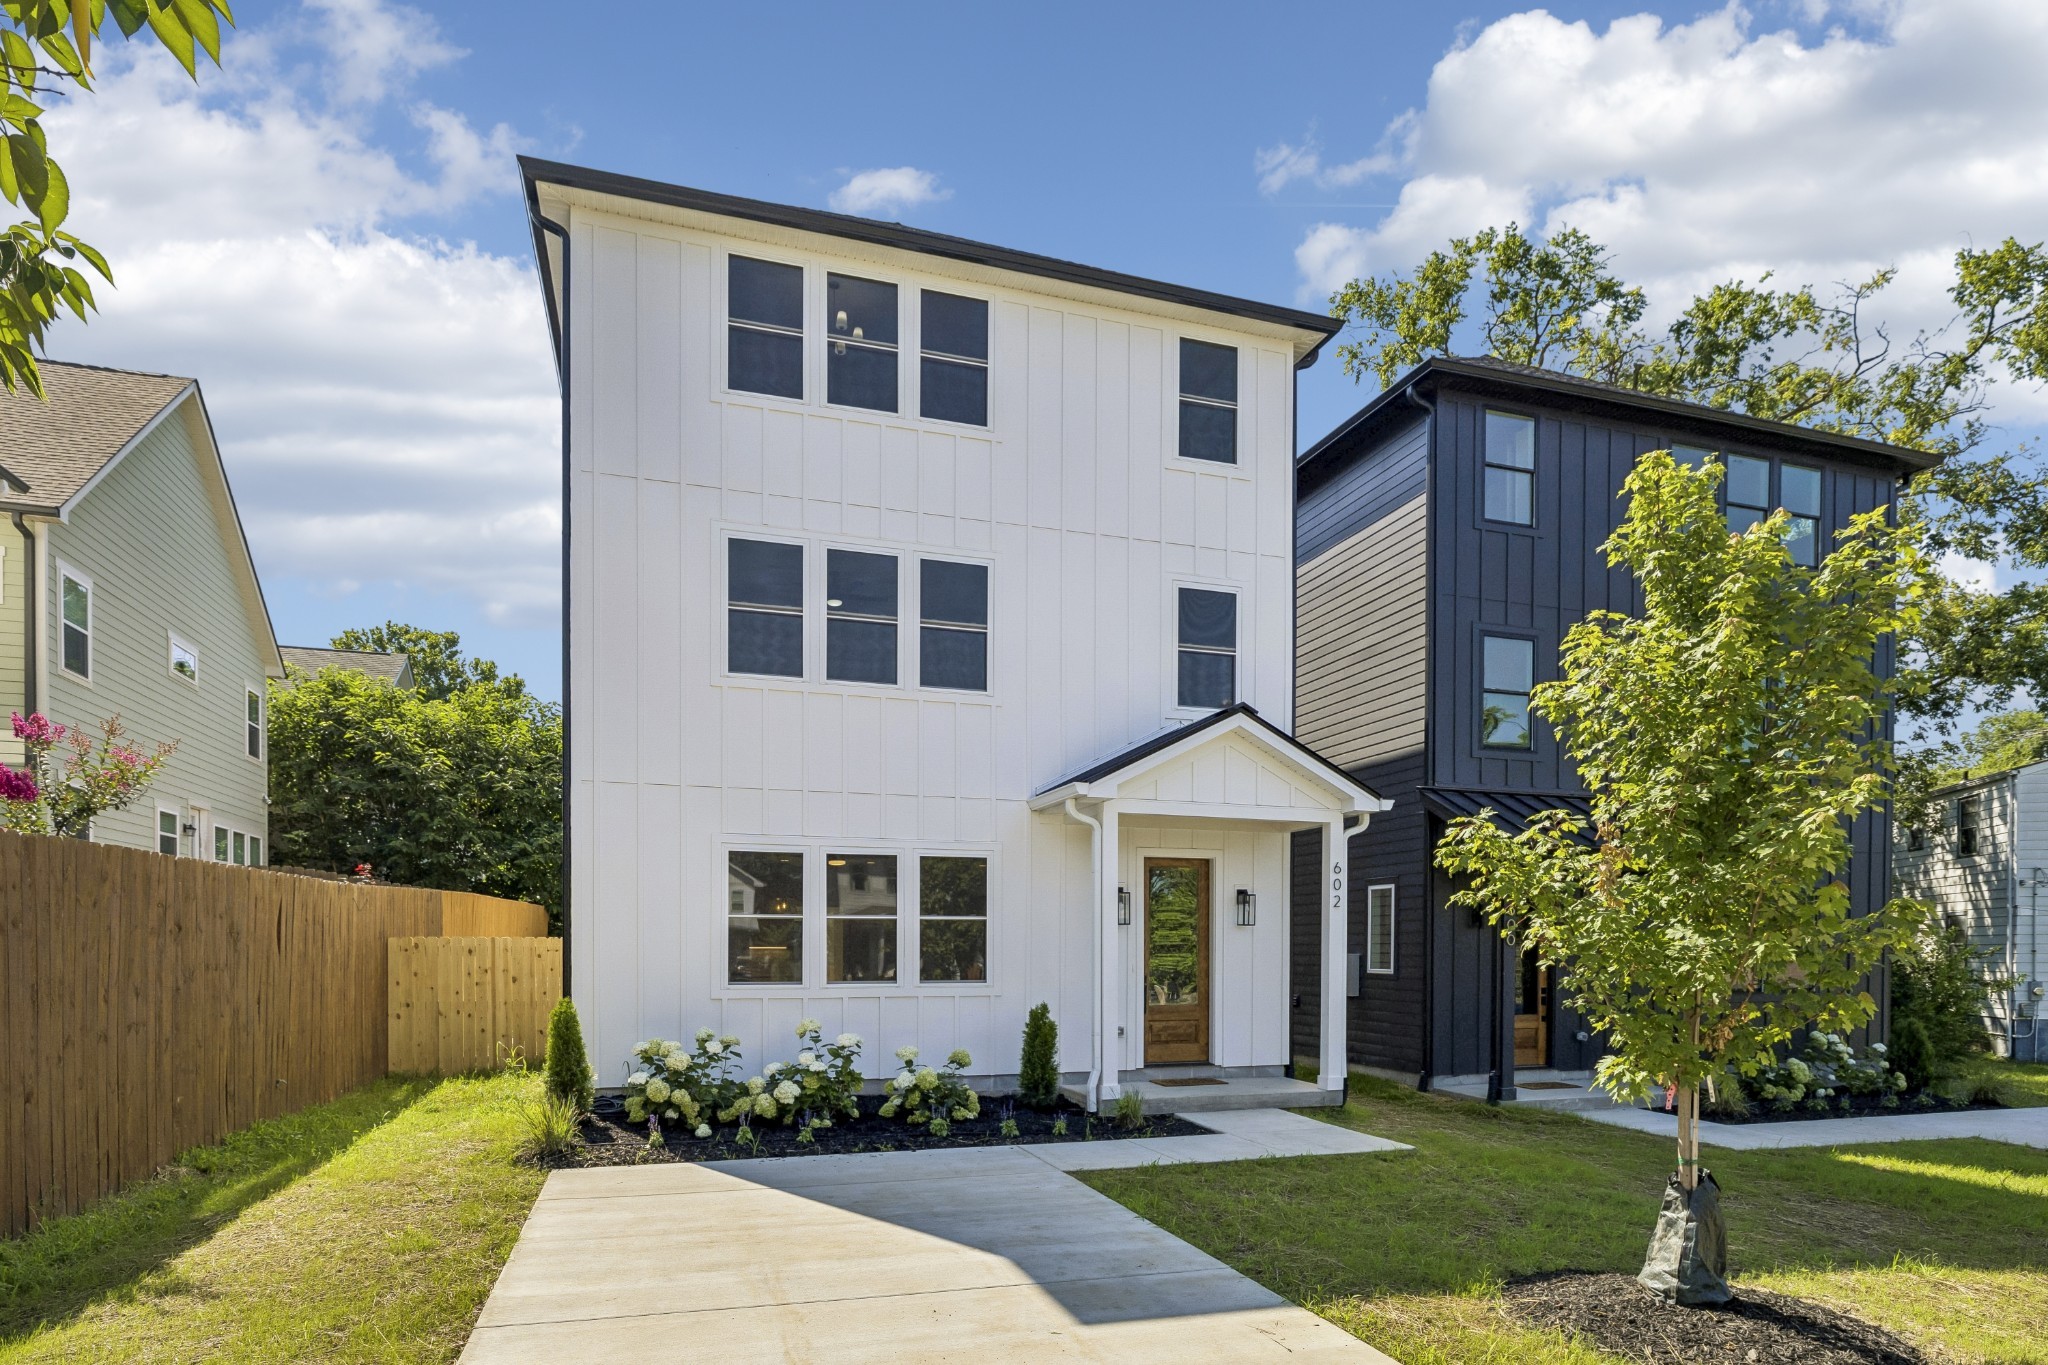
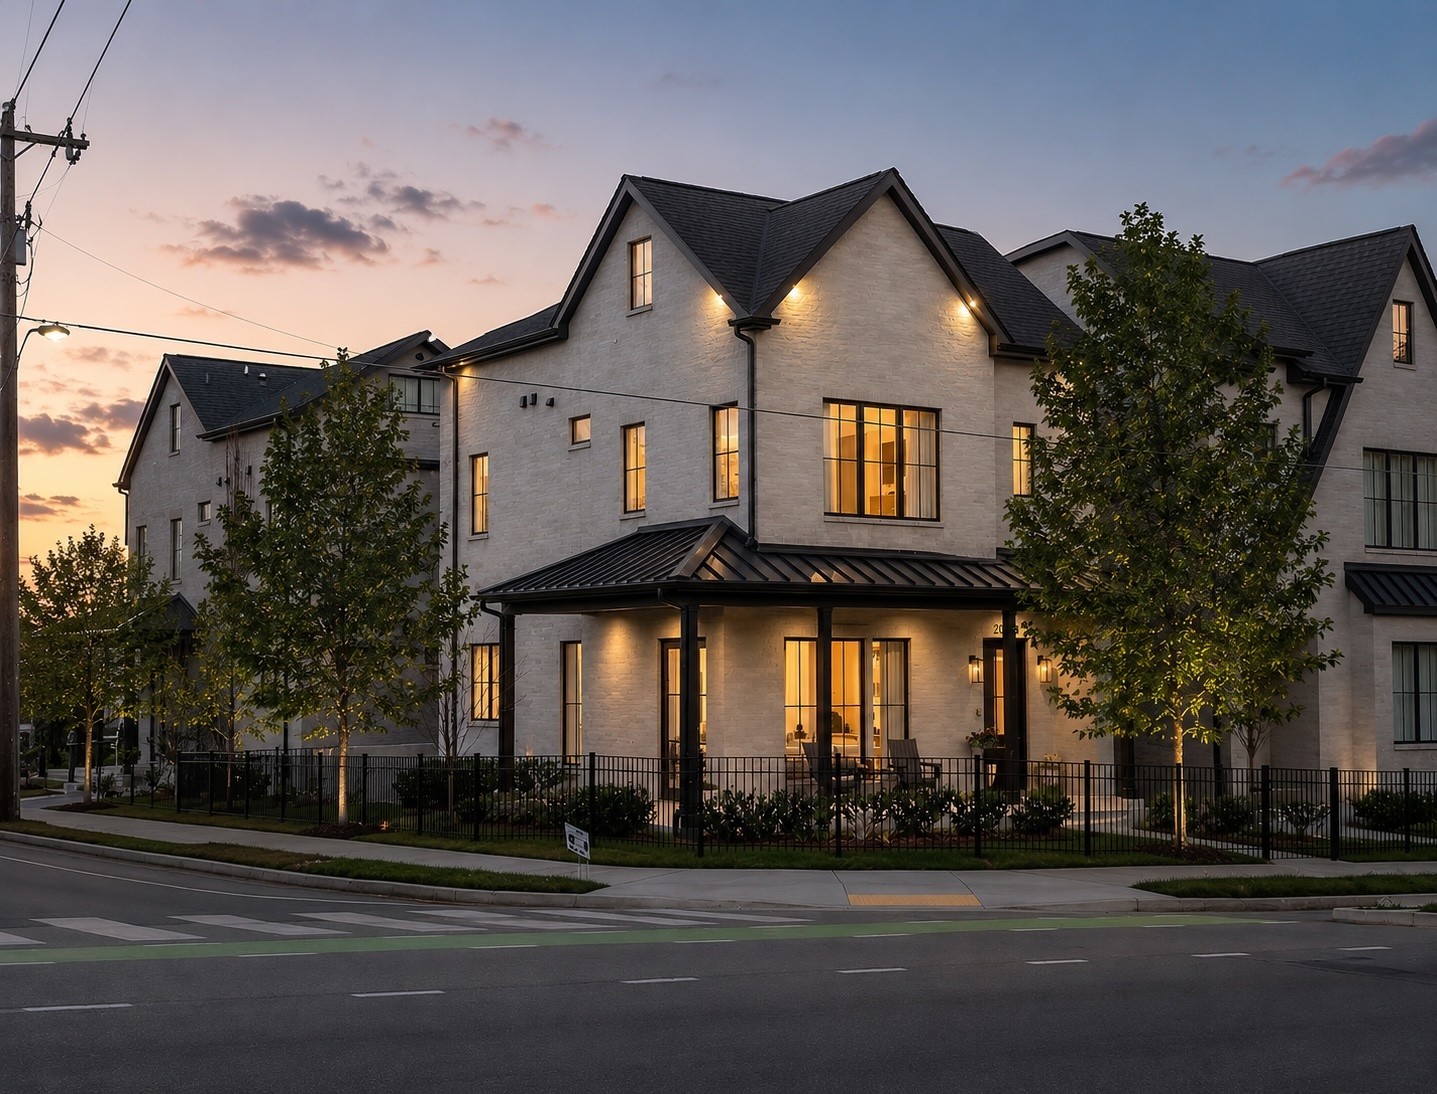
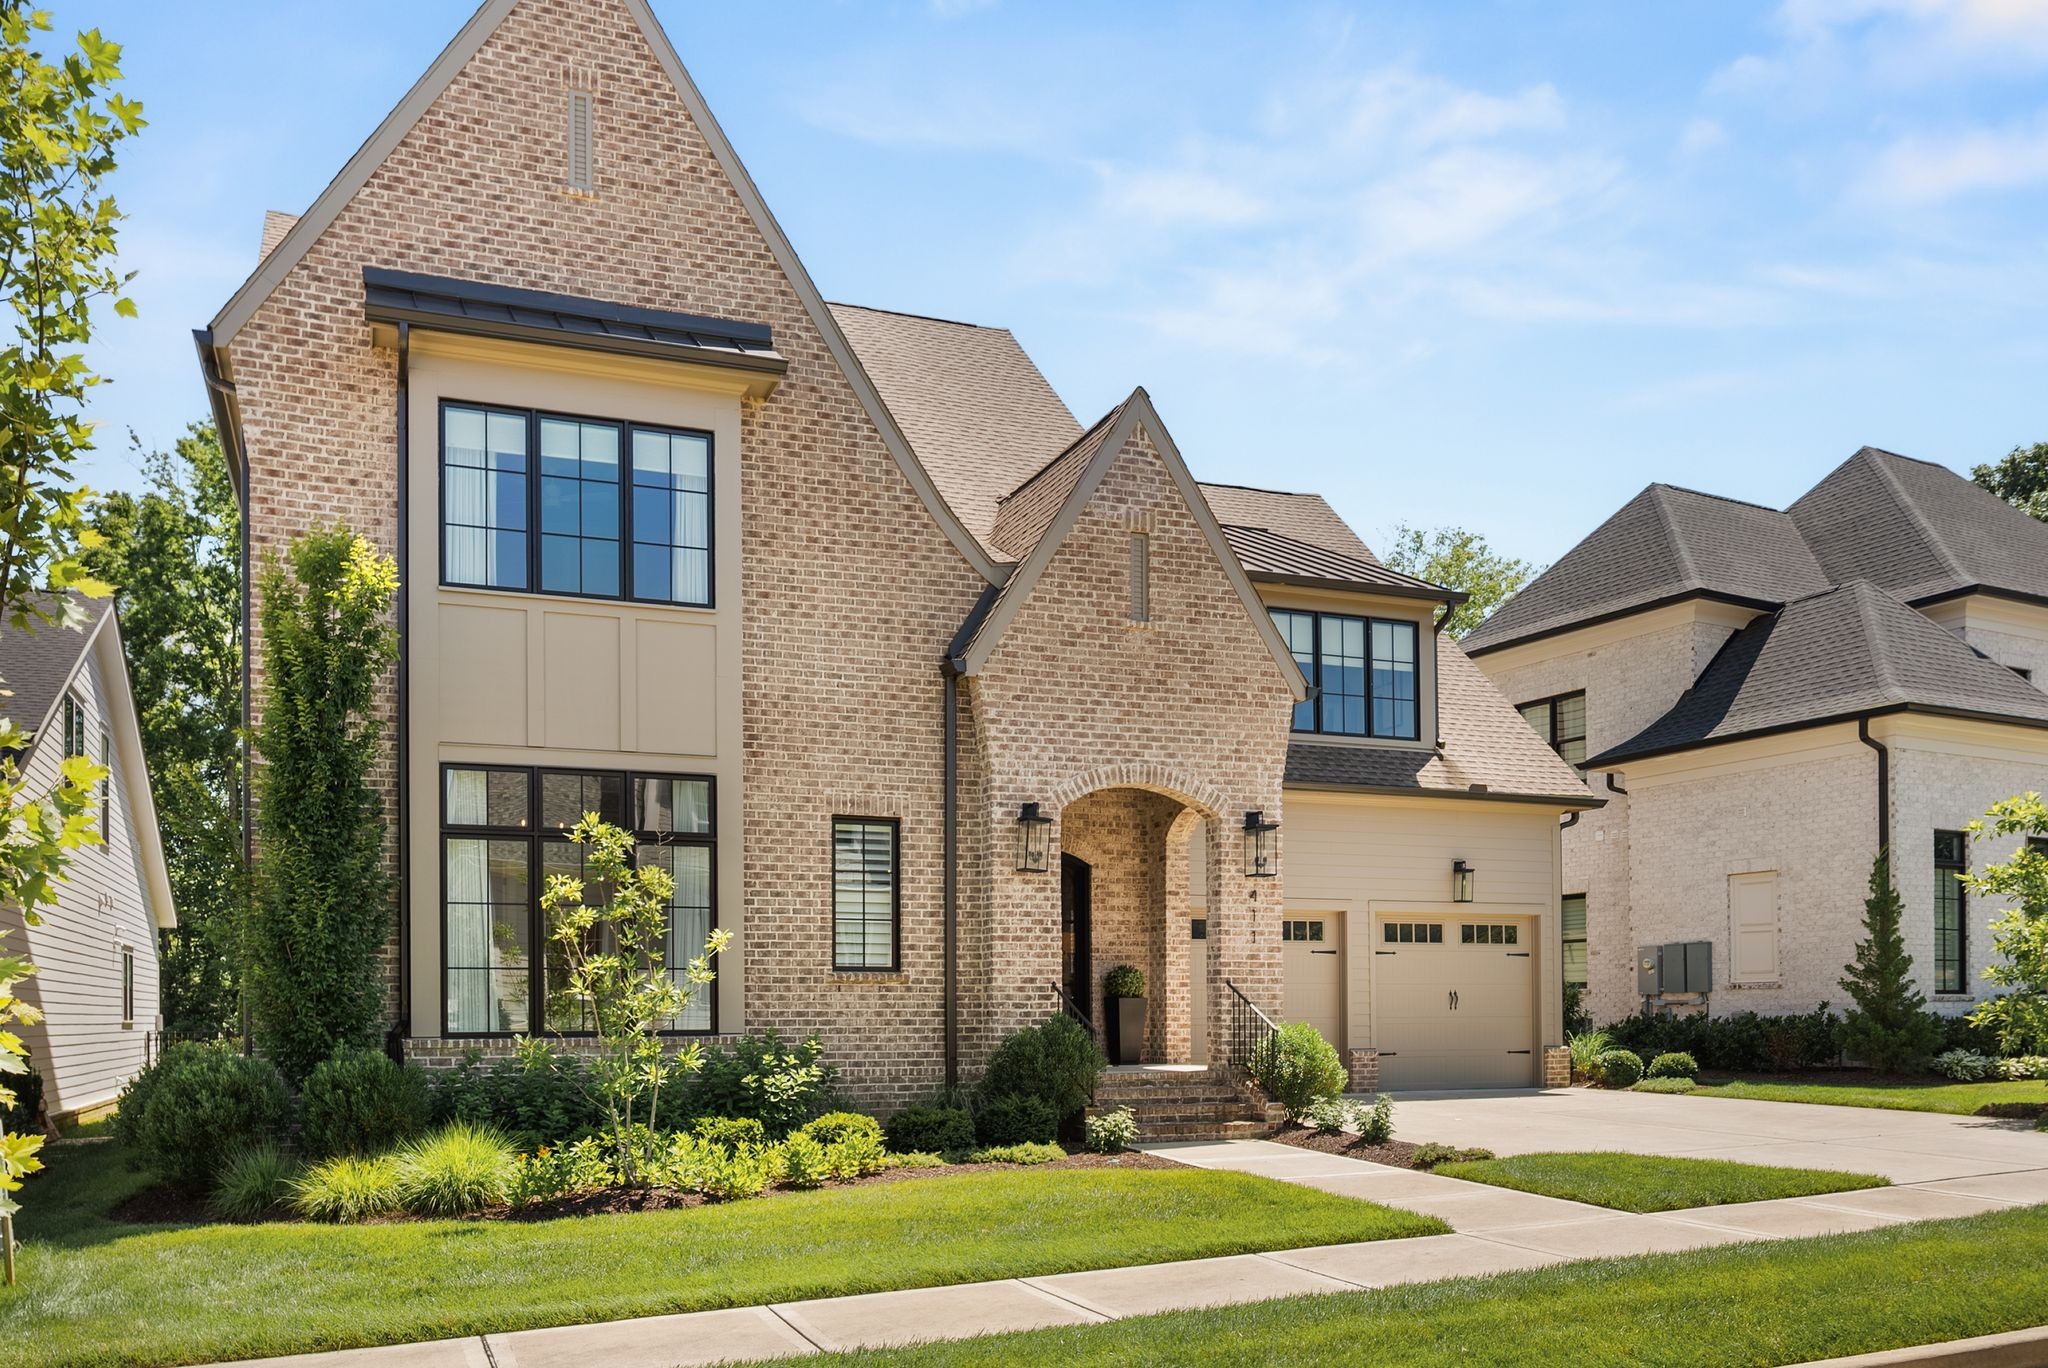
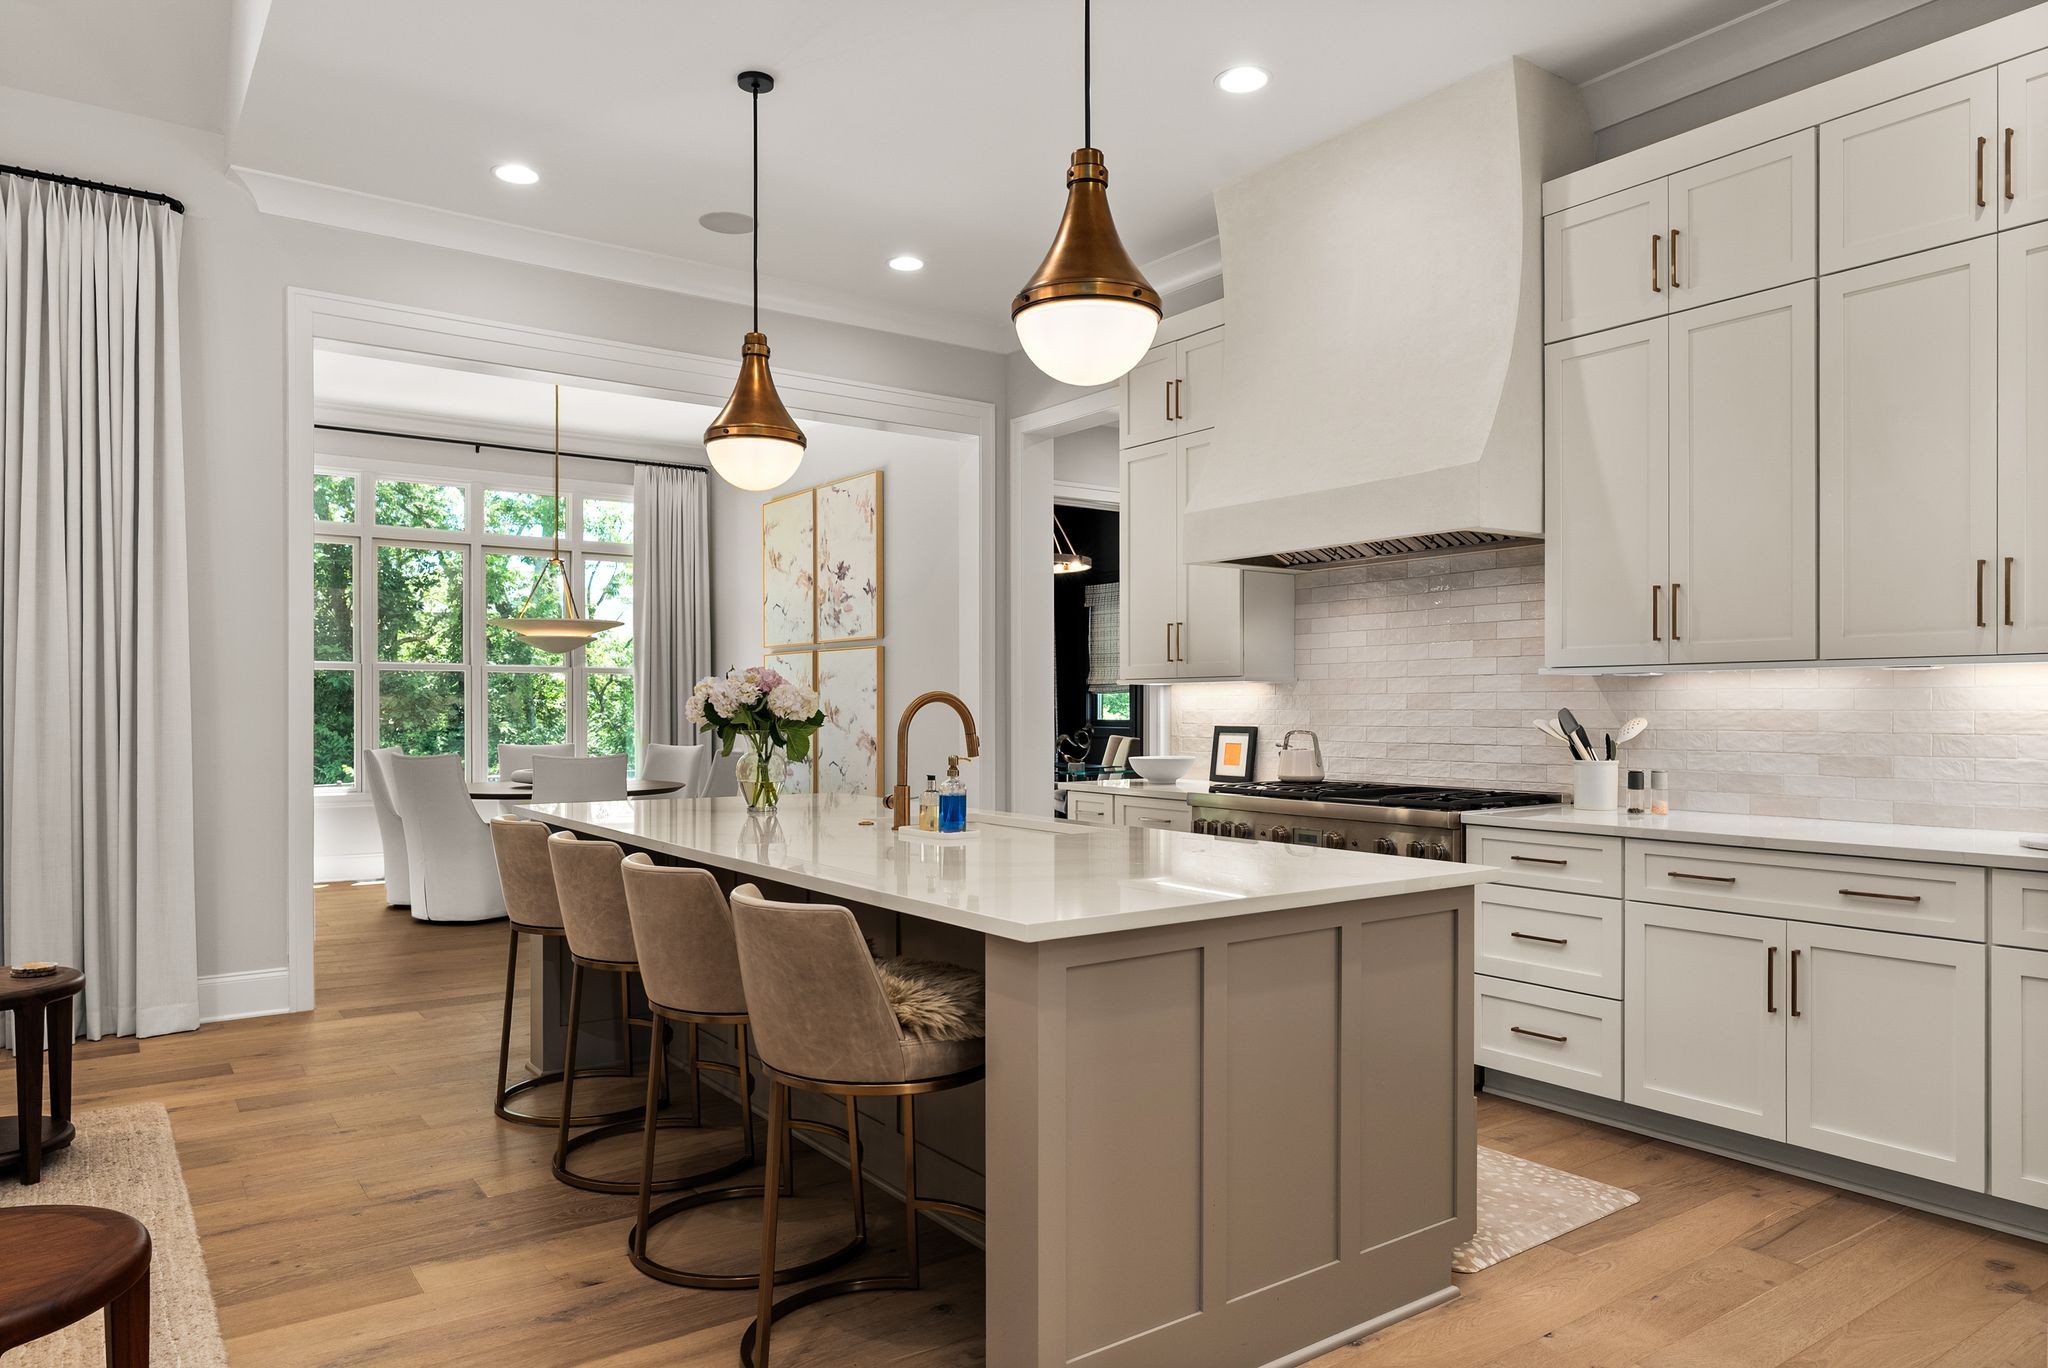
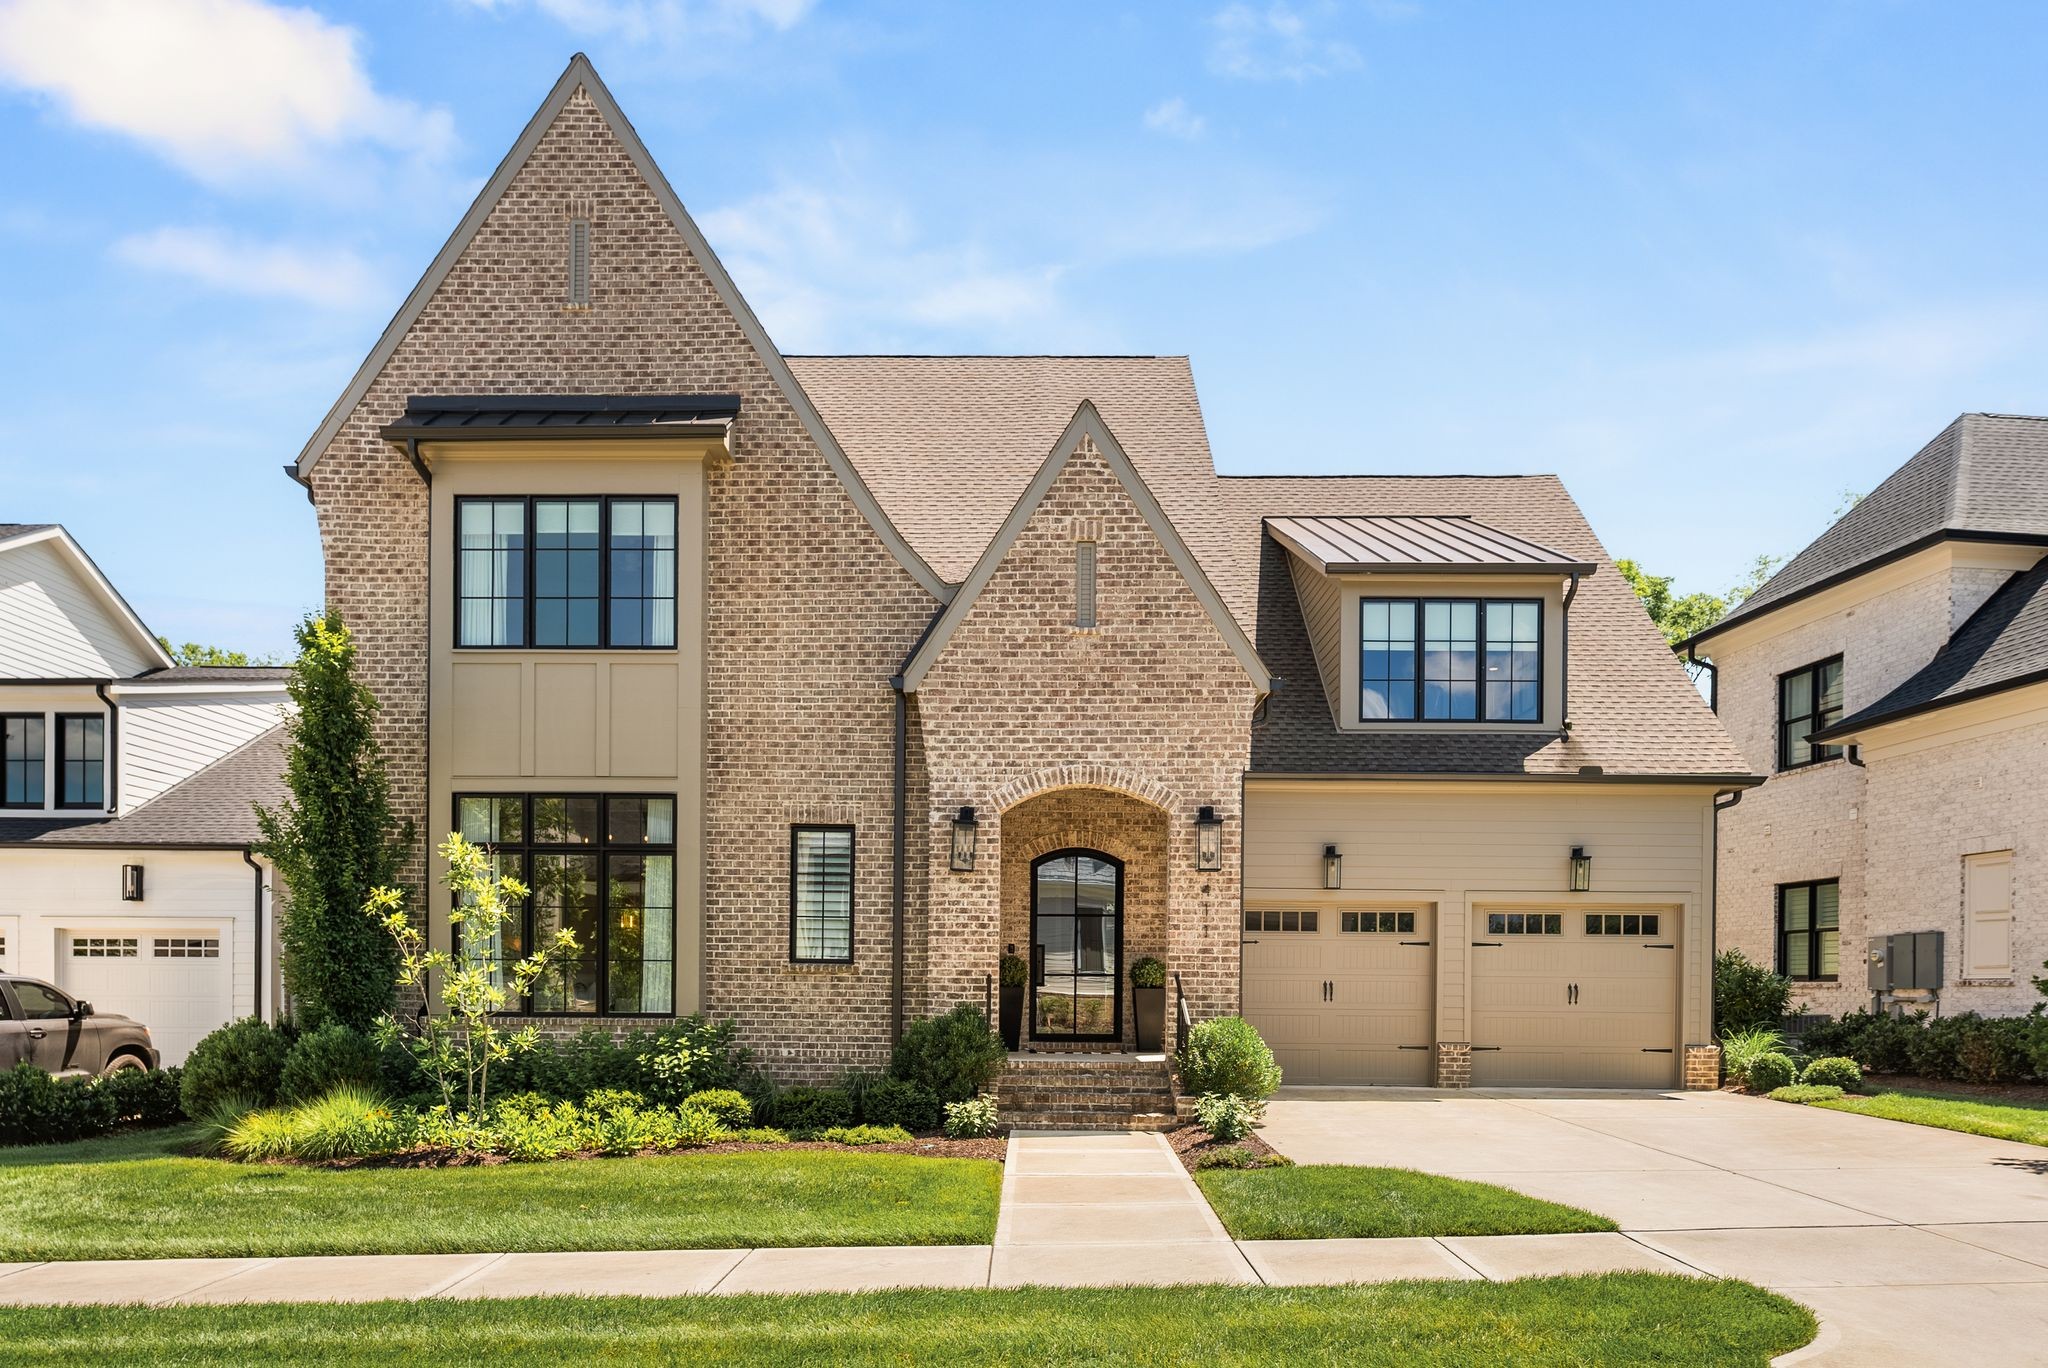
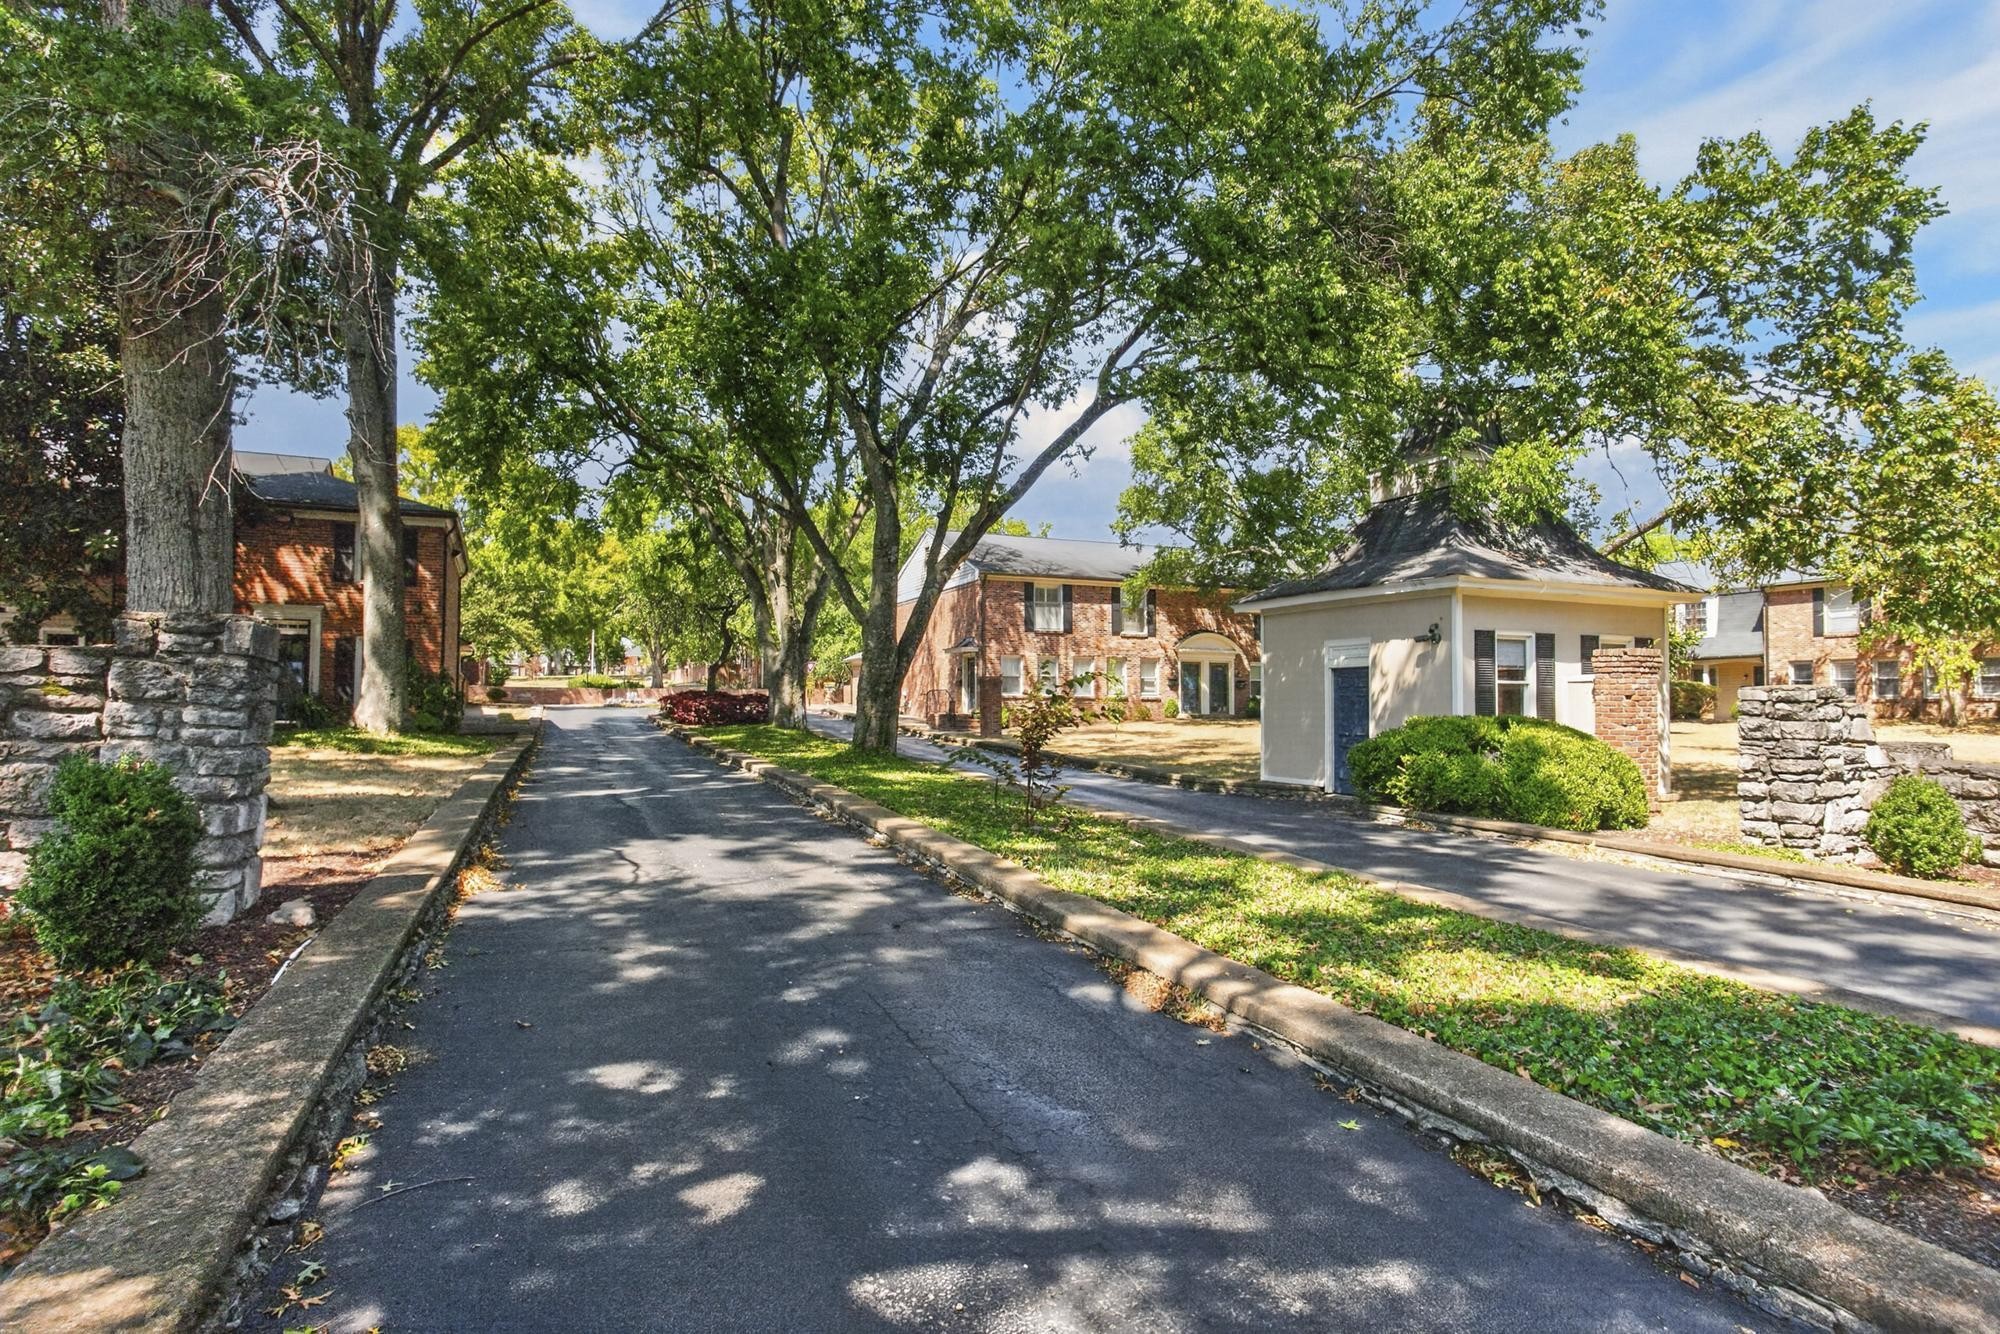
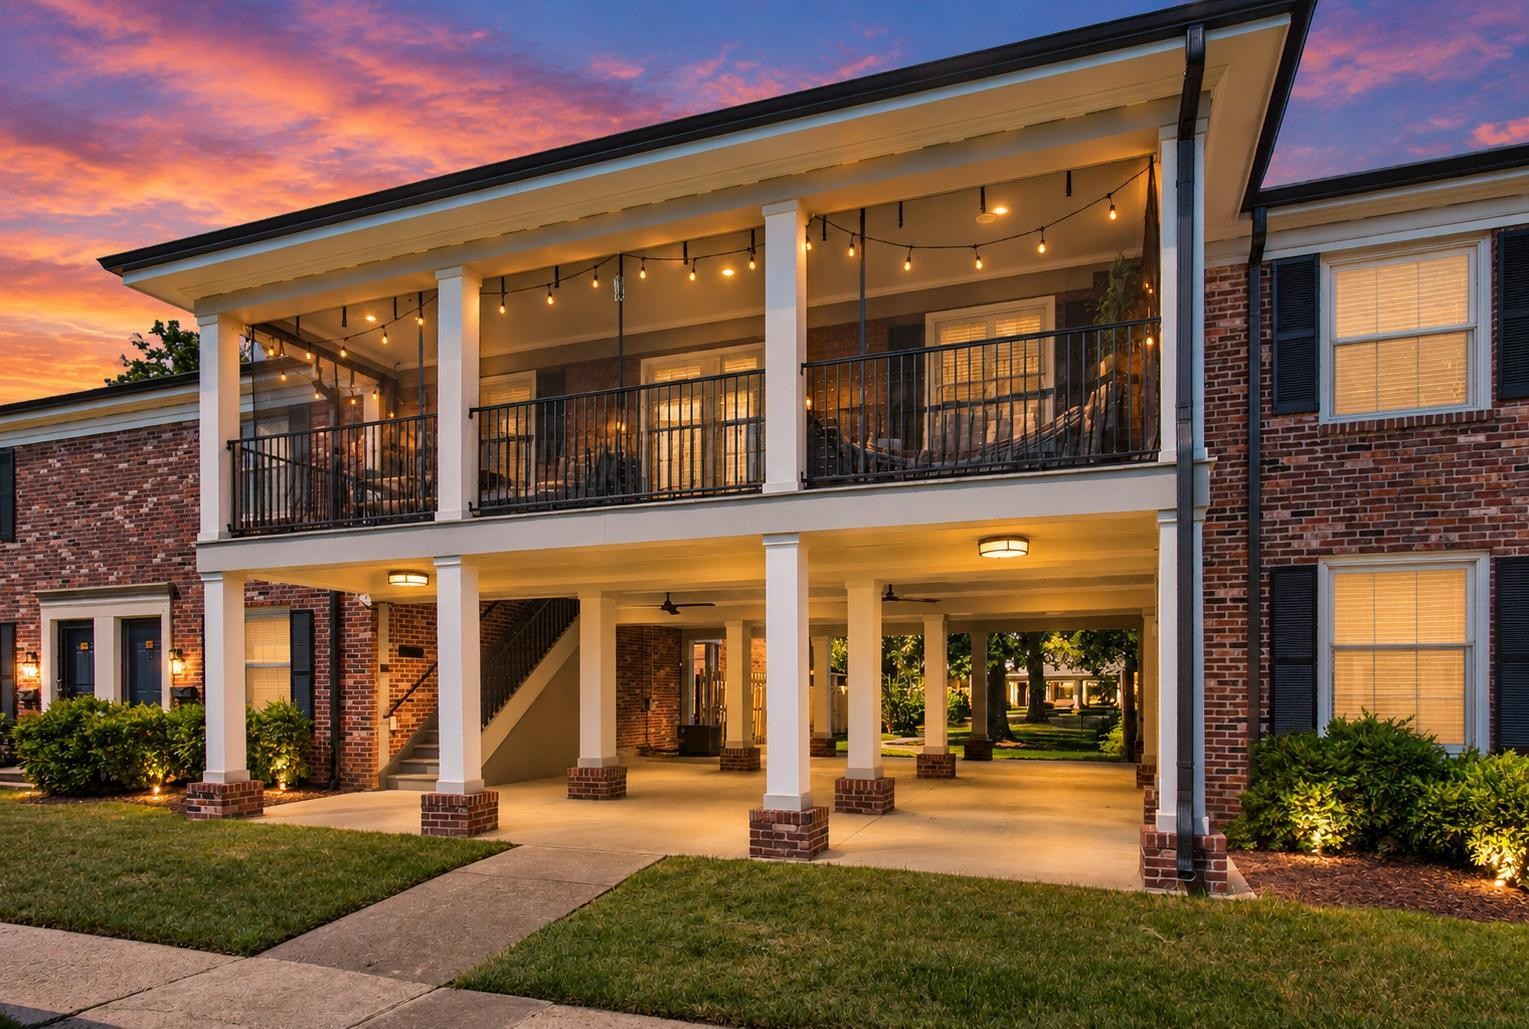
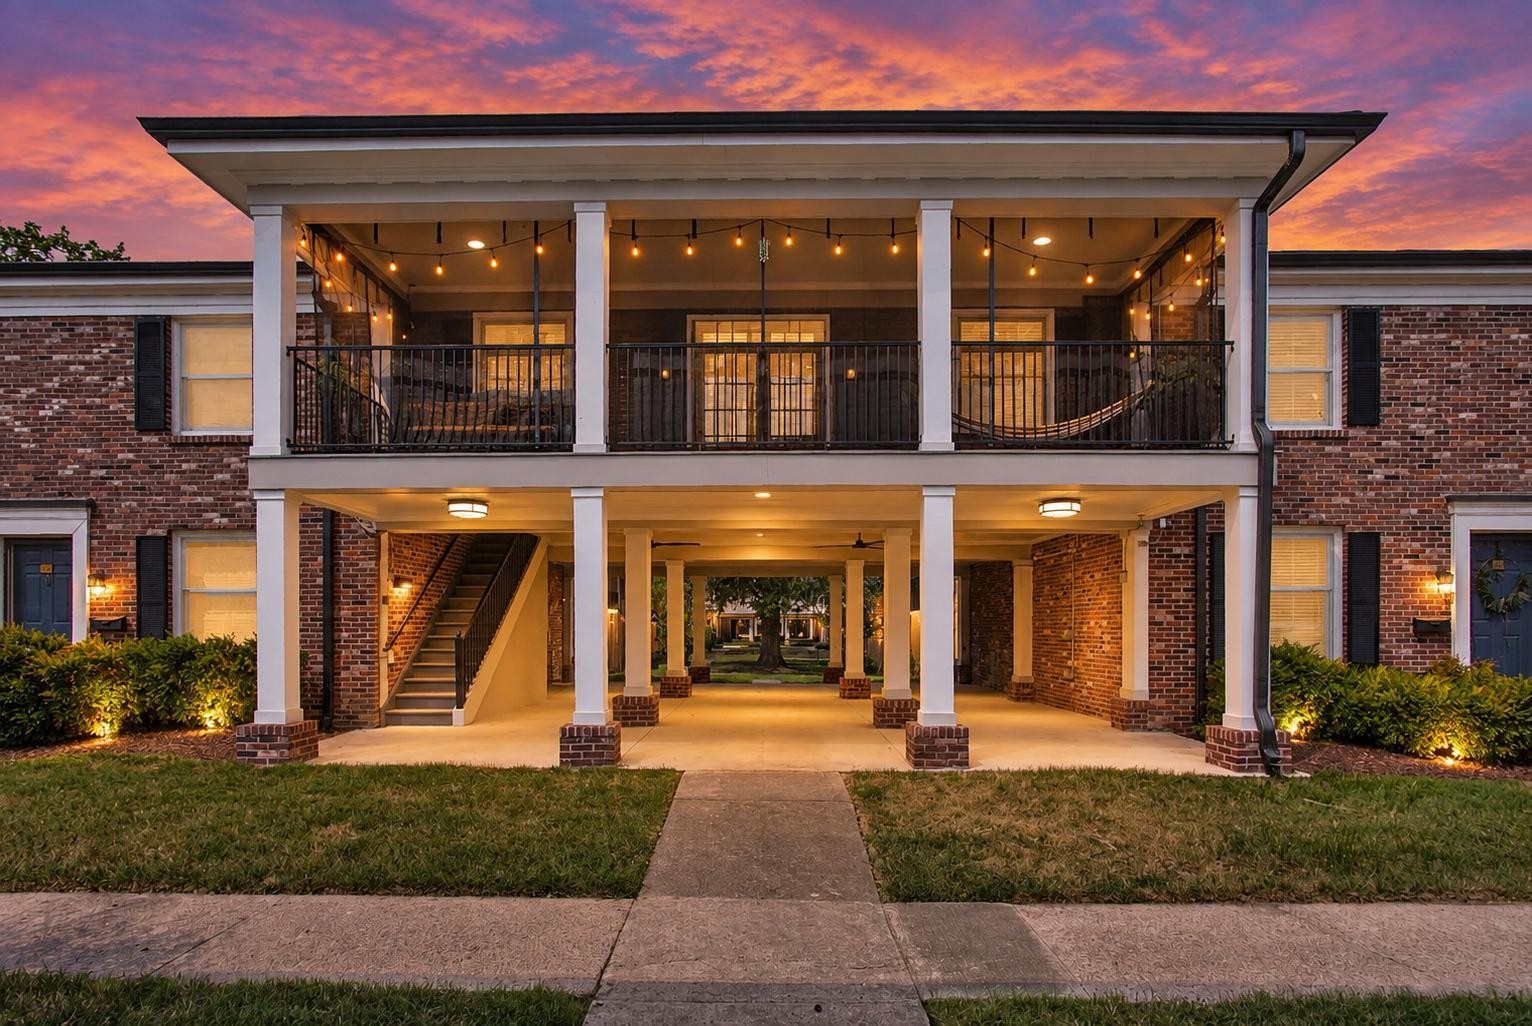
5025 Hillsboro Pike #18G, Nashville, TN 37215
MLS#: 3547792


You do not need 20% down to buy a house in Nashville. Most of the first-time buyers we work with put down somewhere between 3% and 10%, and a good number of them cover part of even that with assistance money they did not know existed six weeks earlier.
Nashville's median single-family price sat at $537,000 in June 2026, with about 51 days on market and six months of inventory across the region. That last number matters more to you than the price does. Six months of supply means you can inspect a house, think about it overnight, and negotiate — which is a different experience than what buyers faced in 2021.
Here is what is available, what the limits are right now, and what changed this fall.
The Tennessee Housing Development Agency runs the program most Nashville first-time buyers end up using. It is a 30-year fixed-rate mortgage delivered through FHA, VA, USDA, or conventional financing, originated by a THDA-approved lender rather than by THDA directly.
These are the numbers people get wrong most often, usually because they are reading a page that has not been updated in two years. In Davidson County as of the current THDA limit schedule:
| Limit | Amount |
|---|---|
| Household income, 1–2 people | $139,320 |
| Household income, 3 or more | $162,540 |
| Maximum purchase price | $500,000 |
Most of the Nashville-area counties we work share Davidson's limits. Maury County runs lower on income — worth checking before you assume a Columbia or Spring Hill purchase pencils the same way a Donelson one does. THDA revises these on its own schedule, so confirm the current figure with your lender before you write an offer rather than trusting any blog post, including this one.
A half-point rate reduction on a Great Choice loan for active military, National Guard, veterans, state and local law enforcement, firefighters, EMTs and paramedics, and full-time K–12 classroom teachers. On a $450,000 loan, half a point is roughly $2,250 a year. It stacks with down payment assistance.
If you qualify for a Great Choice first mortgage, you can layer Great Choice Plus on top of it as a second mortgage covering down payment and closing costs. Two structures:
The ten-year clock on the deferred option is the part buyers misunderstand, and it has real consequences. If rates drop two points in year four and you refinance, that $6,000 comes due at closing. Plan around it rather than being surprised by it. We go deeper in our breakdown of down payment assistance programs for Nashville buyers.
Effective with rate locks beginning September 14, 2026, THDA added a down payment assistance product for newly built homes offering up to $25,000. Four things to know:
That combination changes the math on new construction for a first-time buyer more than it might look. The 120-day lock is the quiet half of it — builder timelines routinely blow past a standard 60-day lock, and buyers who were priced out by a rate that moved during construction now have four months of protection. Because this is brand new, THDA's consumer-facing pages may still show the older $6,000 and $15,000 figures for a while. Ask your lender about it by name.
Not sure which of these you'd qualify for? We'll walk through your numbers and point you to a THDA-approved lender who closes in your county. No obligation, no pressure.
Talk to us first →A conventional option with 3% down and reduced mortgage insurance. The first-time buyer requirement is waived, which makes it the path for repeat buyers who sold a house a few years back and have been renting since. The rate typically runs slightly higher than Great Choice, and the new $25,000 construction assistance does not apply here.
Zero down, no monthly mortgage insurance. Nashville's veteran population is large and the VA Medical Center anchors a lot of it. If you are eligible, this usually beats everything else on this page.
Zero down in qualifying areas. Nashville proper does not qualify, but pockets of Cheatham, Robertson, Wilson, and Rutherford counties do — Ashland City and Pleasant View among them. Eligibility is drawn by map, not by county, so check the specific address.
A federal tax credit worth up to $2,000 a year against mortgage interest, and it can pair with Great Choice.
640 is the floor for Great Choice. Better pricing on conventional financing generally starts around 680, and the best tiers open up at 740. But the thing worth flagging in 2026 is not your score.
THDA has seen enough undisclosed debt from Buy Now Pay Later services that it issued specific guidance to lenders on it. Affirm, Afterpay, Klarna, Zip, and Sezzle balances frequently do not appear on a credit report, which is exactly why they cause problems: if a lender identifies one during the application, it has to be documented with its full terms and outstanding balance, and the monthly payment counts against your qualifying ratio unless the cumulative total is 5% or less of your gross monthly income. Lenders have been told to read bank statements closely looking for them. If you financed a couch or a Peloton over six payments, disclose it up front — finding it at underwriting is how a closing date slips.
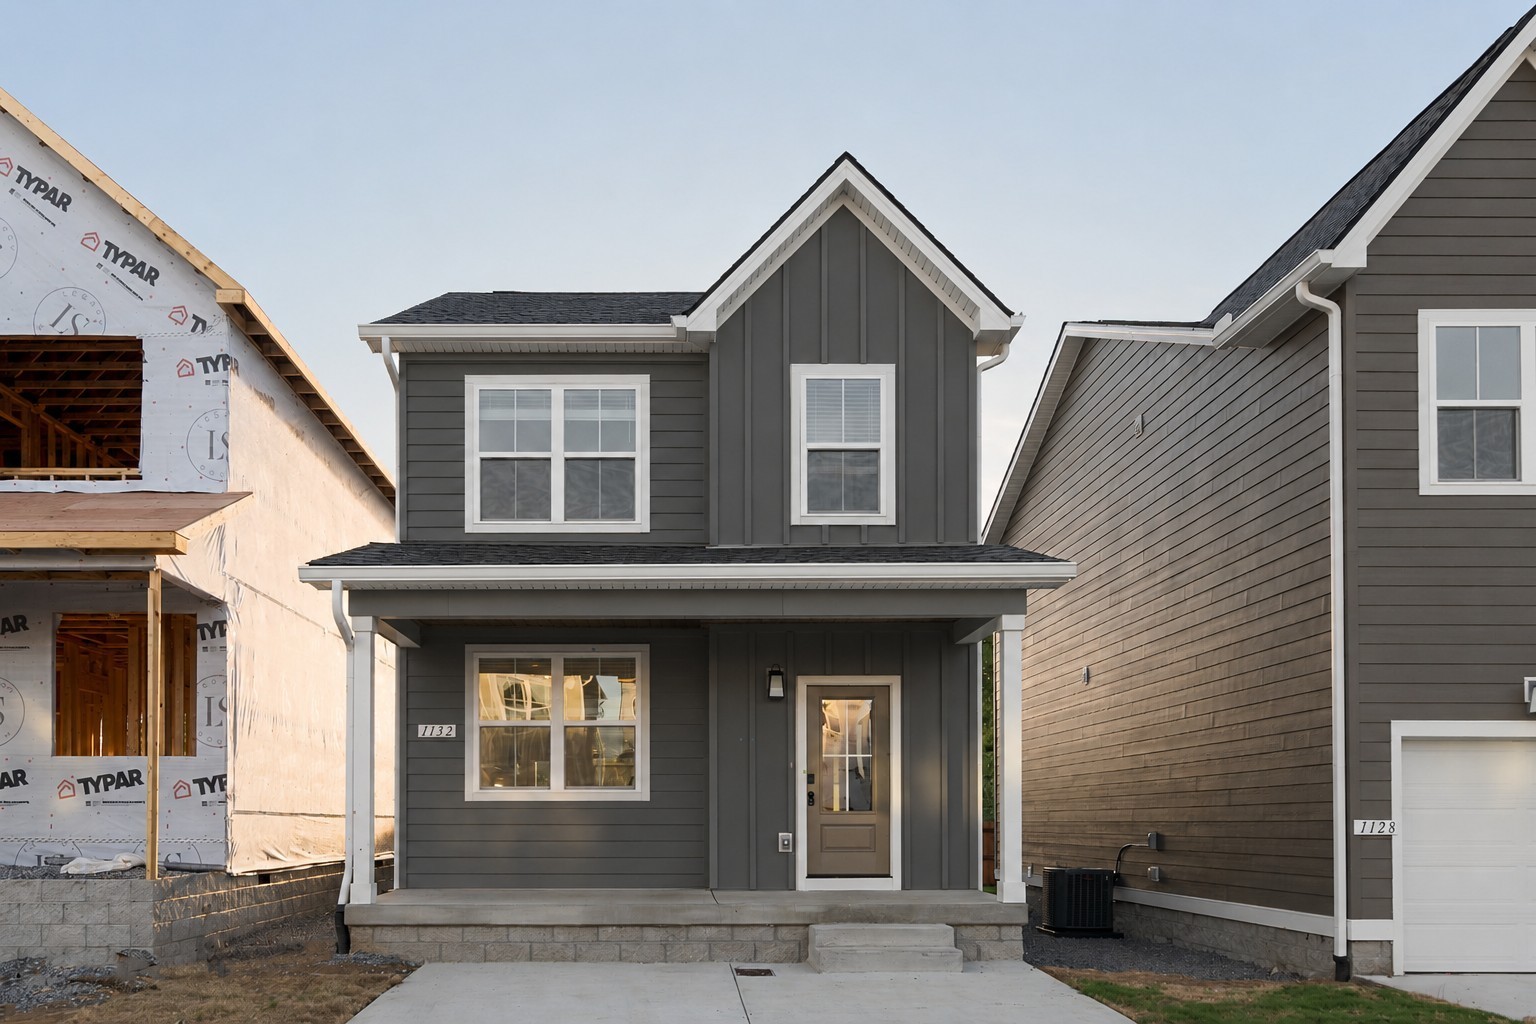
The $500,000 THDA ceiling rules out a fair amount of the in-town market but leaves plenty open:
One structural note on infill and townhomes: a lot of what looks like a detached house in Davidson County is legally an HPR rather than a fee-simple lot, and that affects financing. Worth knowing which one you are looking at before you fall for it.
Assistance money covers down payment and closing costs. It does not cover everything, and our buyer closing costs guide itemizes the full list. Budget for:
Generally, anyone who has not owned and occupied a principal residence in the past three years. There are exceptions — targeted counties and designated areas waive the requirement entirely, and the Freddie Mac HFA Advantage product has no first-time restriction at all. If your spouse owned a home but your name was never on the deed, ask; you may still qualify.
$6,000 on the deferred option, up to $10,000 in some targeted areas, or up to 5% of the sales price capped at $15,000 on the amortizing option. As of September 14, 2026, newly built homes financed under Great Choice or Homeownership for Heroes can access up to $25,000.
Only if you sell, refinance, or transfer the deed inside ten years. Stay past the ten-year term and it is forgiven. This is the detail most buyers get wrong, and it is worth factoring into any plan to refinance if rates fall.
Yes, and as of September 2026 there is a product built for it — up to $25,000 in assistance plus a reinstated 120-day rate lock, available under Great Choice and Homeownership for Heroes but not under HFA Advantage. The 120-day lock matters because builder delivery dates move.
They can. THDA now directs lenders to document any Buy Now Pay Later obligation found during the application and count the monthly payment in your qualifying ratio unless the cumulative total is at or under 5% of gross monthly income. These balances often do not show on a credit report, so lenders are reviewing bank statements for them. Disclose them at the start.
Great Choice will not work yet. A THDA-approved counselor can build a plan to get you there, and for many buyers that is a matter of months rather than years. Worth starting that conversation before you begin touring.
Most first-time buyers we meet have been scrolling listings for months and have not yet talked to a lender. That order costs people houses. Thirty minutes on the phone will tell you which of these programs fits, what your real monthly number looks like, and whether the $25,000 new-construction option is worth steering toward.
James walks every property. Stephanie handles strategy, contracts, and negotiation. No hand-offs, no assistants, no junior agent you have never met turning up at your closing.
Call or text (615) 751-8913, or get in touch here.

James & Stephanie Crawford are Nashville natives who have helped Middle Tennessee neighbors buy and sell homes since 2003 — 500+ closings and counting. James handles every showing and appointment; Stephanie handles strategy, contracts, and negotiation. No hand-offs, no assistants, start to close.
Nesting Realty | (615) 751-8913 | nestinginnashville.com/contact
Equal Housing Opportunity. This article is for general information and is not legal, tax, or financial advice. Program terms, income and purchase price limits, and market data change. Confirm eligibility, current limits, and loan terms with a THDA-approved lender before making decisions. Broker compensation is fully negotiable and not set by law.